Optimized rates for a profit target
Calculates the rate that achieves the profitability target your bank has preset, deal by deal, so nothing is quoted below it by accident.
Banking product price optimization
BankSpread embeds credit risk, customer's relationship, liquidity risk and your bank's profitability into every single deal to calculate the optimized interest rate that hits your profit target. See the P&L behind each deal and Agentic Repricing. Built for the relationship manager's negotiating table.
The challenge
Most banks still price off a rate card, a spreadsheet and heuristic decision making.
RMs negotiate price off a rate card and gut feel
Likely revenue leakage in every deal
Pricing deals may not be fully auditable
Regulators expect defensible pricing
Risk may veto a high NIM, low RAROC deal
Wasted RM effort and customer churn
Limited or no option to reprice an ongoing account
Revenue loss
Products are priced in silos
No tailored offer, unhappy customers
Excel-based manual pricing
Longer turnaround and prone to error
The solution
BankSpread calculates the rate, tests the alternatives, documents the deal and routes it to the right approver, with every step on record.
Calculates the rate that achieves the profitability target your bank has preset, deal by deal, so nothing is quoted below it by accident.
Makers can create a deal at a different price from the optimized one. A detailed P&L report shows exactly how far the simulated rate moves profit.
Generates the credit memo for the deal. The maker downloads it, edits it if required and sends it to the checker for approval.
Prices multiple products together against the customer's overall relationship with the bank, blending loans, lines of credit and deposits into a single relationship-level target.
Set inputs by business line, product and customer segment, and the solution prices from them. Makers can still override the preset values on a deal.
Signals whether a deal is profitable after risk adjustment and flags it when it is not, before it reaches approval.
Risk-based pricing
Risk is priced in from the first calculation, not added after the quote, so the rate your relationship manager offers is the one that holds up at approval.
The expected loss from the customer's credit profile.
The cost of funding and regulatory outflow rate to off-balance sheet commitments
The customer's overall standing with the bank across products.
The profitability target the rate has to achieve.
Priced on all four, in potentially every deal.
Reports
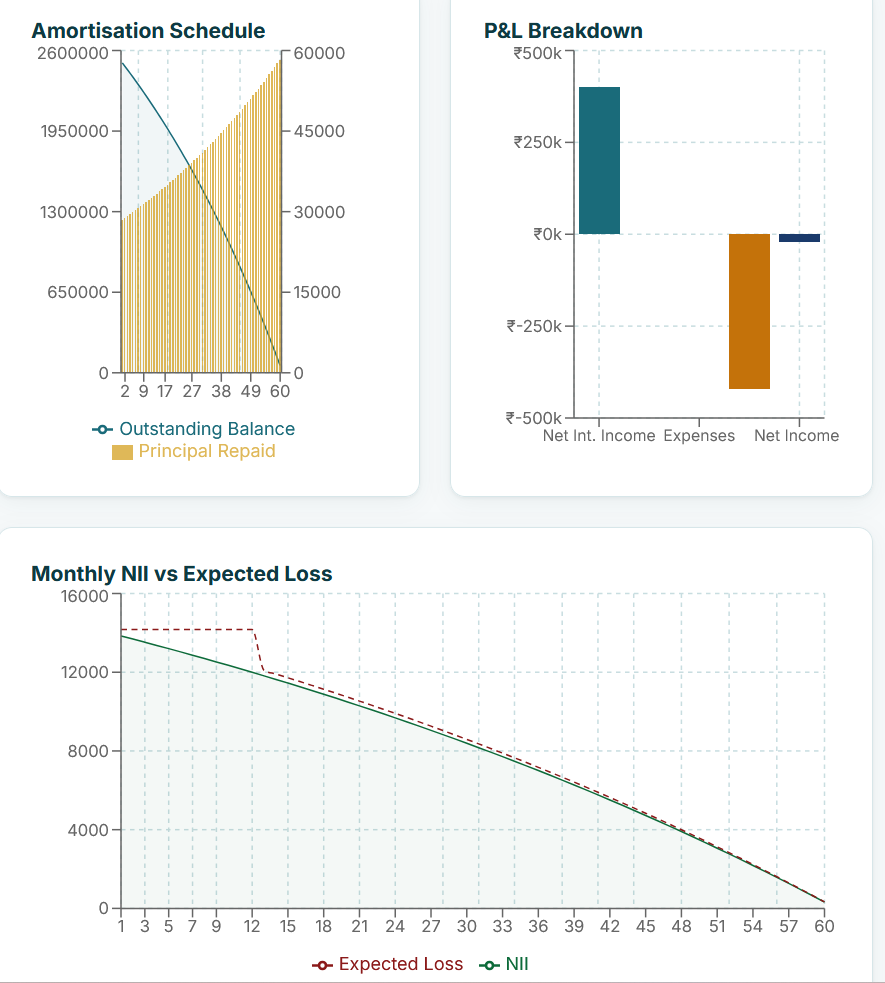
See how a deal earns over its life: the repayment curve, the income and expected loss (where applicable) month by month, and an income statement that rolls up to net income.
From target to rate, or from rate to profit
The solution computes the rate. You give a target; it returns the risk- and relationship-based price that meets your profitability goal.
You enter a rate directly. The solution does not compute a rate; it computes what your rate earns.
Products and structures
Five banking products are priced today, with the repayment and rate structures that real corporate and SME deals need.
Current and savings account pricing
Fixed-tenor deposit pricing with interest accrual options
Term lending without collateral
Term lending against collateral
Revolving limits without collateral
Supports complex bespoke corporate loan structures.
Applied to loan pricing across the supported products.
Rate guardrails
Define a floor and a ceiling for every product and customer segment. When a computed rate falls outside the range, the maker and the checker are warned before the deal moves on.
Agentic repricing
A deal's profitability drifts as inputs change. Rules catch the drift and run multi-step orchestration. AI agent works each flagged deal step by step and recommends the optimal fix.
The system tracks existing deals against target margin as any input changes.
Deals whose profitability has fallen below target are flagged automatically.
Repricing is run through multiple simulations for each flagged account.
ML model predicts the best repricing strategy and advises the price maker.
Governance and compliance
BankSpread is a maker-checker solution. No deal goes live until a checker approves it, and the audit trail keeps every deal defensible.
The outcome
Estimated for India small finance banks.
Faster pricing with minimum manual effort.
A full audit trail behind every priced deal.
*Estimate assuming 10 bps improved spread.
Margin protected on every deal, with less manual pricing effort.
Grow customers and revenue with sharper, relationship-level offers.
Deals that fail risk-adjusted returns are flagged before approval.
Every deal's pricing decision is on record.
Book a walkthrough and we will price a deal from your book, show the P&L behind it and the maker-checker flow based approval.
Tell us where to reach you and we will set up a walkthrough.